Slot Farms Exploit Bingo Hall Loophole to Dodge Tax
Adult gaming centres in England use bingo licences to avoid higher business rates. Budget tax rise faces loophole challenge.
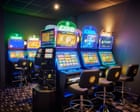
Slot Farms Navigate Tax Increase Through Regulatory Gaps
The bingo hall loophole represents a significant challenge to government efforts to increase taxation on the gambling industry. Hundreds of adult gaming centres across England continue to benefit from discounted business rates by maintaining bingo hall licences, despite operating primarily as slot machine venues. This regulatory gap threatens to undermine recent tax policy changes designed to generate additional revenue from the gambling sector.
Finance Minister John Healey recently announced substantial changes to gambling taxation in his latest budget announcement. The government raised the duty on slot machine takings from 20% to 25%, marking a significant increase in the tax burden on gaming operators. Healey's stated objective was to redirect gambling industry profits toward supporting economic development and revitalising struggling retail districts across the nation.
Understanding the Business Rates Advantage
Adult gaming centres have traditionally benefited from preferential business rate assessments when holding bingo hall licences. These reduced rates reflect the historical treatment of bingo as a social gaming activity, distinct from other forms of gambling. However, many establishments registered as bingo halls now generate the majority of their revenue from electronic gaming machines rather than traditional bingo operations.
The financial incentive for maintaining this classification is substantial. Businesses holding bingo licences can secure significantly lower business rate bills compared to facilities categorised purely as gaming venues. This cost differential provides a powerful motivation for slot machine operators to retain their bingo hall status, even when bingo represents only a marginal component of their actual business activities.
The Scale of the Regulatory Challenge
Industry analysis suggests that hundreds of locations across England exploit this regulatory loophole. These establishments operate what critics describe as slot farms—high street venues dominated by electronic gaming machines—while technically qualifying for bingo hall business rate discounts. The practice effectively shields substantial portions of the gaming industry from the full burden of the new tax measures.
The concentration of these venues along retail high streets raises particular concerns. Local communities host gaming establishments that contribute less to local authority finances than their operations might suggest. This creates a dual problem: reduced tax revenue and potential negative social impacts on town centres.
Government Policy Intentions and Implementation Gaps
Healey's budget initiative specifically targeted adult gaming centres as part of a broader strategy to increase revenue from gambling activities. The policy rationale emphasised fairness and growth, suggesting that increased taxation on gambling would fund productive economic initiatives. However, the existence of the bingo hall loophole means that a significant segment of the targeted sector may effectively circumvent the new duty requirements.
The gap between policy intention and practical implementation highlights the complexity of gambling regulation. While tax rates on slot machine takings have increased, the underlying business rate structure remains unchanged, creating parallel tax systems that reward regulatory classification over actual business operations.
Closing the Loophole: Policy Options
Addressing this regulatory gap would require legislative intervention or regulatory clarification. The government could implement several approaches to ensure that adult gaming centres cannot claim bingo hall status without genuine bingo operations. Options include establishing minimum thresholds for bingo revenues relative to total gaming revenues, requiring independent verification of business classifications, or eliminating the bingo hall business rate discount altogether.
Each approach presents different implementation challenges and potential unintended consequences. Policymakers must balance the objective of capturing additional revenue from the gaming industry against practical enforcement concerns and potential impacts on legitimate bingo operations.
Broader Implications for Tax Policy
The bingo hall loophole exemplifies broader challenges in tax policy implementation. Regulations developed for historical contexts may create unintended opportunities for avoidance when circumstances change. The gaming industry has evolved significantly since business rate classifications were originally established, creating misalignment between regulatory categories and actual business models.
This situation underscores the importance of regulatory review and adaptation. Tax and rate structures must evolve alongside industry developments to maintain policy effectiveness and fairness. Without such adjustments, well-intentioned revenue measures may fail to achieve their intended outcomes while creating incentives for continued regulatory exploitation.
The resolution of the bingo hall loophole will likely emerge as a key test of the government's commitment to the stated objectives behind the gambling tax increase, determining whether policy changes translate into meaningful revenue generation or whether regulatory gaps continue to undermine enforcement.